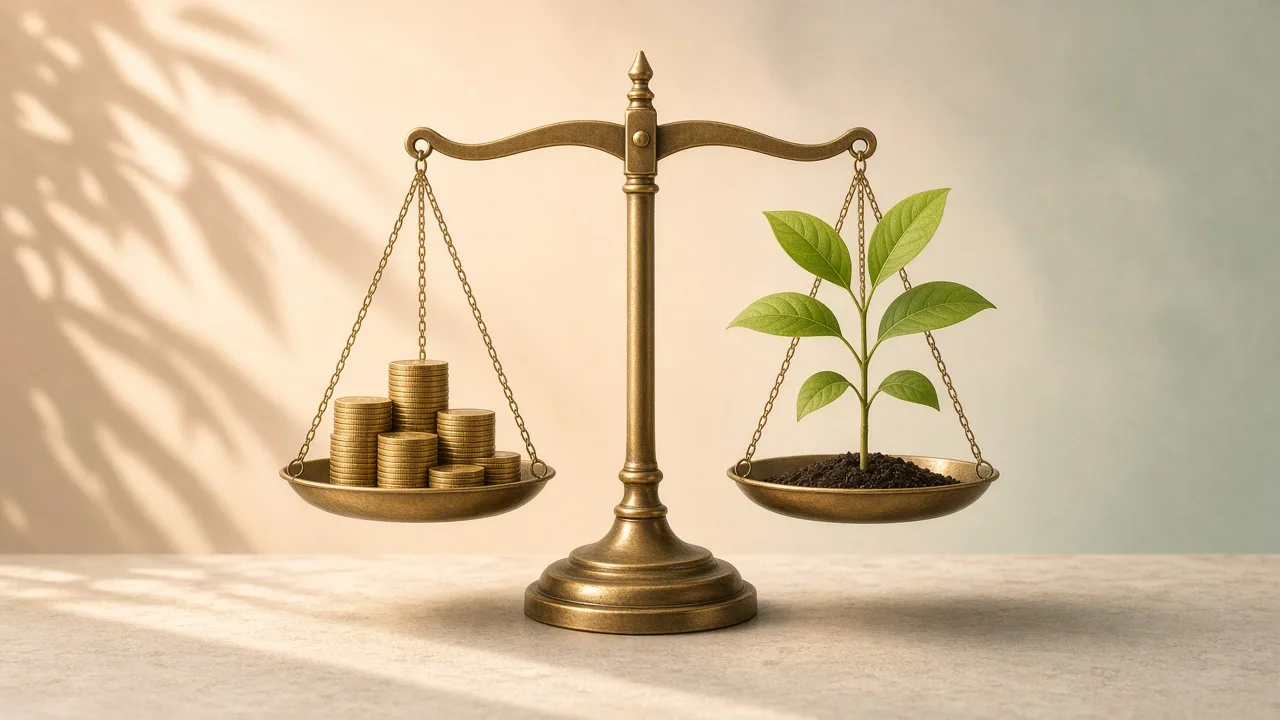
You may have started investing with a clear plan, perhaps a certain share in equity funds and the rest in debt. A few years later, after a strong market run or a sharp fall, that mix can look very different. Rebalancing is the simple discipline of bringing your portfolio back to the allocation you chose.
Why allocations drift
Different assets grow at different speeds. When equities rise faster than debt, they gradually take up a larger share of your portfolio. That can feel good, but it also means you are carrying more risk than you originally decided you were comfortable with. When equities fall, the opposite happens and your portfolio may become too conservative to meet long-term goals.
What rebalancing achieves
- Keeps risk in line with your plan. Your allocation reflects your goals and comfort with ups and downs; rebalancing preserves it.
- Builds a sell-high, buy-low habit. You trim what has done well and add to what has lagged, without trying to predict markets.
- Reduces emotional decisions. A rule-based approach replaces impulse with routine.
Two common methods
Calendar rebalancing means reviewing your portfolio at a fixed interval, such as once a year, and adjusting if needed. It is easy to remember and avoids constant tinkering.
Threshold rebalancing means acting only when an asset class drifts beyond a set band from its target, for example a few percentage points either way. It responds to large market moves but requires you to keep an eye on your numbers.
Many investors combine the two: check once or twice a year, and rebalance only if the drift crosses their chosen band.
Ways to rebalance
- Redirect new money. Point fresh SIPs or lump sums towards the underweight asset. This avoids selling and is often the gentlest option.
- Switch between funds. Move money from the overweight asset to the underweight one.
- Use withdrawals. If you are drawing money for a goal, take it from the overweight portion.
Mind taxes and costs
Selling investments can trigger capital gains tax, and some funds charge an exit load if redeemed within a certain period. Before rebalancing, check the holding period of each investment, the applicable tax treatment and any exit loads. Using new contributions to rebalance, or rebalancing within tax-advantaged accounts where possible, can reduce these costs. Tax rules change from time to time, so verify the current position or consult a qualified professional.
Rebalancing as goals approach
Your target allocation is not fixed forever. As a goal such as a child's education or retirement comes closer, many people gradually reduce equity exposure to protect what they have built. This planned shift, sometimes called a glide path, is different from routine rebalancing but works alongside it.
Common mistakes
- Rebalancing too often and paying unnecessary taxes and loads.
- Abandoning the plan after a big rally because equities "seem unstoppable".
- Ignoring smaller holdings such as gold or international funds when calculating allocation.
- Looking at each goal's money separately without seeing the overall picture, or vice versa, without a clear method.
A simple annual routine
Once a year, list all your investments, group them by asset class, calculate each share of the total and compare it with your target. Note any drift beyond your band, decide whether new contributions can fix it, and make switches only where necessary. Write down what you did so next year's review is quicker.
Wrapping up
Rebalancing is unglamorous, but it keeps your portfolio aligned with the plan you made when you were calm and thoughtful. Choose a method, respect taxes and costs, and let the routine do the work.
Note: This article is for general information only and is not financial advice.